Resiliq Launches Quant Lab: Quant Models for Private Markets
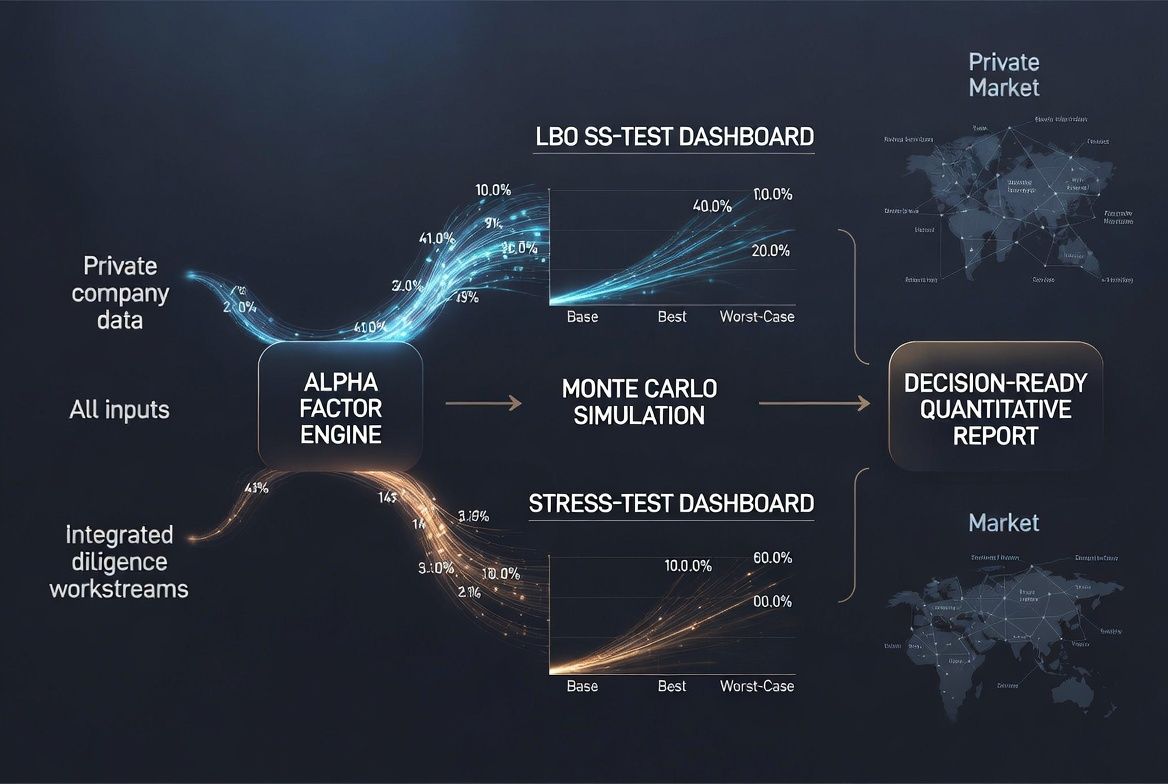
Today, we are making Quant Lab generally available to all Resiliq platform users. Quant Lab is a purpose-built quantitative modeling environment designed from the ground up for private markets – where data is sparse, financials are irregular, and traditional tools routinely fall short.
Why Private Markets Need Purpose-Built Quantitative Modeling
Private markets professionals have long relied on spreadsheets, ad-hoc databases, generic financial software, or expensive in-house quant teams to run the kind of rigorous quantitative analysis their investment decisions require. These approaches are slow, error-prone, and difficult to scale across a portfolio of active deals.
Quant Lab addresses this gap directly. It provides an integrated modeling environment within the Resiliq platform, offering pre-built quantitative models and scenario simulation capabilities that are specifically calibrated for the conditions of private markets – illiquid assets, limited comparable data, and non-standard financial reporting.
Pre-Built LBO, Credit Stress, and Monte Carlo Simulation Engines
Pre-built models: A library of ready-to-use quantitative models covering LBO analysis, credit stress testing, LP/GP waterfall modeling, Monte Carlo deal simulation, and advanced AI/ML models. Each model is tuned to work reliably with the kind of incomplete and irregular data common in private markets.
Alpha factors: A curated set of alpha factors for screening and ranking investment opportunities across sectors, geographies, and deal types. These factors are a mix of private-market and common public market signals applicable to privates.
Scenario simulation: Run sensitivity analyses and stress tests across multiple deal parameters simultaneously. Understand how changes in entry multiples, leverage ratios, growth assumptions, or exit timing affect returns under realistic or not yet known private-market conditions.
Integrated workflow: Quant Lab is not a standalone tool. It is tightly integrated with the rest of the Resiliq platform – AI agents, deal & market research, due diligence, and portfolio monitoring – so quantitative insights flow directly into decision-making workflows.
Under the Hood: Monte Carlo LBO & Risk Simulation Parameters
Quant Lab allows deal teams to configure institutional parameter envelopes for complex deal simulations:
- Capital Structure & Tranches: Senior secured, unitranche, mezzanine debt, and sponsor equity modeling with automated interest rate compounding and amortisation schedules.
- Multi-Variable Stochastic Paths: 10,000-iteration Monte Carlo simulations across correlated revenue growth, margin compression, and terminal exit multiple distributions.
- LP/GP Waterfall Engine: European and American waterfall structures with preferred return hurdles, catch-up tranches, and carried interest splits calculated deterministically.
Quantitative Analysis Calibrated for Sparse and Irregular Private Data
Most quantitative tools available today were designed for public markets, where data is abundant, standardized, and continuously updated. Private markets operate under fundamentally different conditions: limited historical data, non-uniform reporting, and long holding periods with infrequent pricing events.
Quant Lab is built to handle these realities. Its models are calibrated for sparse-data environments, its simulation engine accounts for illiquidity and irregular cash flows, and its output formats are designed for the reporting needs of PE, VC, and alternative asset professionals.
Accelerating Private Equity Underwriting and Diligence Workflows
With Quant Lab, deal teams no longer need to choose between speed and rigor. An analyst can run a full LBO sensitivity analysis on a target company, stress-test the capital structure under multiple scenarios, and generate a decision-ready output – all within the same platform they use for sourcing, diligence and portfolio work.
This eliminates the friction of switching between tools, reduces the risk of model errors from manual data transfers, and ensures that quantitative analysis is grounded in the same data that drives the rest of the deal workflow.
Platform Availability and Integration
Quant Lab is available now to all Resiliq platform users. Existing users can access it directly from their workspace. New teams can request access through support.
We will continue to expand the model library and simulation capabilities based on feedback from our users and the evolving needs of private markets professionals.
Explore Solutions
Private Equity
Private equity software for deal sourcing, company research, due diligence, LBO and M&A modelling, and portfolio decision support.
Private Credit
Private credit software for borrower research, underwriting, covenant analysis, stress testing, and portfolio risk decision support.
Hedge Funds
Private market research, quantitative modelling, factor analysis, and portfolio risk workflows for institutional investment teams.
Family Offices
Family office software for deal research, due diligence, multi-asset portfolio context, quantitative scenarios, and investment decision support.
Related Articles
Beyond Chat: The Case for Governed AI-Native Quant Systems
Why private capital deal teams need deterministic quantitative engines rather than conversational chat and RAG for defensible investment decisions.
27 August 2026
AI in PE and VC: From Faster Research to Reviewable Decisions
How AI accelerates PE and VC workflows: automate repeatable company screening, coordinate multi-stream due diligence, and keep financial models reviewable.
15 November 2024
Data-Driven Decisions in Private Equity and Venture Capital
Transform sparse private market data into high-conviction investment decisions. Combine investor judgment with quantitative modeling and verified audit trails.
10 February 2026